Opening a fashion store involves considerable upfront investment in interiors, inventory, rentals, manpower, marketing and other operating expenses. With these costs rising and consumers having more choices, retailers need to be more disciplined about how quickly a new outlet is expected to become profitable.
But store profitability is not simply a question of how much a store sells. It also depends on how efficiently a retailer manages inventory, space and margins. The quality of the location, store productivity, margins, inventory efficiency and the amount of capital invested all influence whether an outlet is commercially viable.
A useful starting point is to distinguish between operating break-even and full investment payback. A store can become EBITDA-positive within a few months while still requiring considerably more time to recover the money spent on setting it up. Current industry expectations suggest that operating break-even can be achieved within the first three to six months, while full capital recovery may take roughly 18–24 months, depending on the format and location.
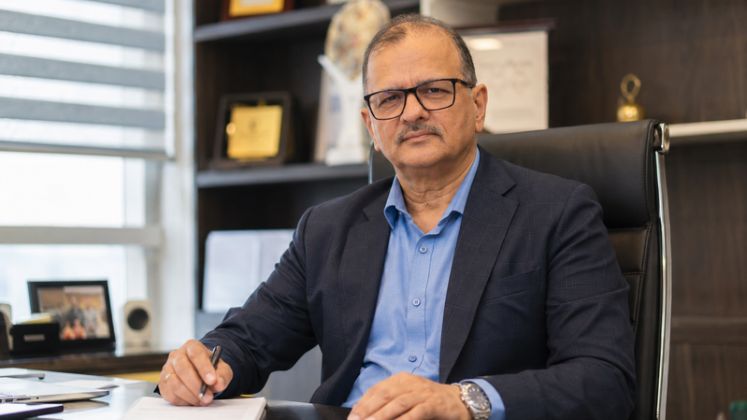
“A healthy fashion store today should hit operating break-even, meaning EBITDA positive, somewhere between 3 to 6 months. Full capital payback, that means recovering everything spent on interiors, lease and setup, should happen within 18 to 24 months,” said Sandeep Kapoor, CMD, SHR Lifestyle, an ethnic wear brand that manufactures and retails everyday wear for women. Shree currently operates 120+ stores across India and international markets, including Dubai, Sharjah, Abu Dhabi, Riyadh and Singapore.
Location Sets the Payback Equation
Location is one of the strongest determinants of store economics. High-street outlets with strong visibility and natural footfall can mature faster, while stores in emerging catchments may take longer to build awareness. Similarly, lower rentals and fit-out costs in Tier 2 and Tier 3 markets can support faster capital recovery, while prime metro locations may generate higher sales but require significantly greater investment. Mall locations can provide more consistent footfall and access to a defined customer profile, but typically come with higher rental and CAM costs.
“High-street stores in Tier 2 and Tier 3 cities recover the fastest, usually in 12 to 18 months. Prime metro malls and high streets in Tier 1 cities take longer, 24 to 30 months, even though footfall and sales start strong from day one,” Kapoor added.
Store size should also be determined by productivity rather than simply by available space. Retailers need to consider sales productivity, store-level EBITDA or contribution, inventory turns, rent-to-sales, gross margin and total capex before finalising the format.
First Six Months: Validate the Store
The opening months should be treated as a period of learning rather than an immediate test of mature-store performance. New outlets can initially benefit from launch promotions, curiosity and local visibility, resulting in an unusually high level of footfall. As this effect fades, the underlying performance of the location and proposition becomes clearer. During the first six months, retailers should track footfall, conversion, average transaction value, units per transaction, sales per sq. ft., product mix and inventory ageing. These indicators help establish whether the right customers are visiting the store and whether the proposition is converting that traffic into profitable sales.
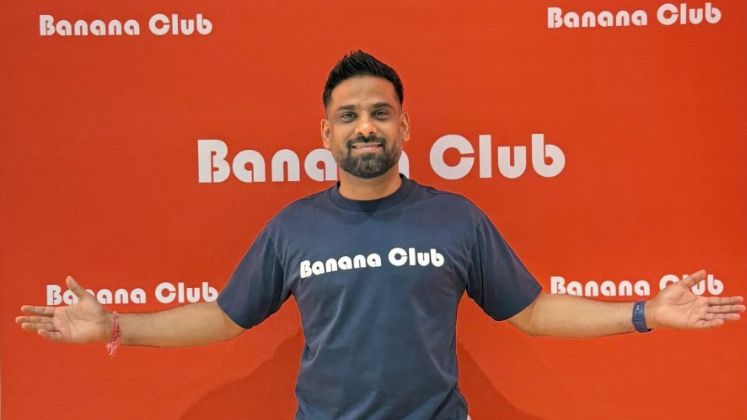
“The first six months are really about validating the location. We closely track footfall, conversion, average transaction value, units per transaction and sales per sq. ft., while also keeping a close eye on product mix, gross margin, repeat customers and inventory ageing,” said Neel Bafna, Founder, Banana Club. The men’s fashion brand, known for its party-wear shirts, oversized tees, co-ord sets and bottom wear, currently operates 22 stores across India.
The trend is often more important than the absolute number in the first few months. A store that starts below its eventual potential but improves consistently can be healthier than one that opens strongly and then experiences a sustained decline. Footfall may stabilise relatively quickly, while conversion and basket size can take longer as customers become familiar with the brand and its offering.
Six to 12 Months: Test the Unit Economics
Once the initial settling-in period is over, the focus should move towards the underlying economics of the outlet. Month-on-month sales growth, gross margin, store contribution, inventory turns, rent-to-sales and markdown dependency become more important.
Retailers should also assess whether customers are returning without requiring continuous promotional support. A healthy store should gradually develop a repeat customer base, while inventory should move at a rate that limits ageing and excessive discounting.
A recent knowledge report by Vector Consulting Group found that 24% of on-shelf Apparel & Footwear products remain beyond their optimal selling window, highlighting how ageing inventory can quietly erode store productivity and profitability.
Productivity benchmarks can provide an additional layer of evaluation. Depending on the category and format, annual sales productivity of around ₹10,000–₹12,000 per sq. ft., rent at approximately 12–15% or lower of sales, and a high share of full-price sell-through can indicate stronger unit economics. These should be treated as reference points rather than universal thresholds.
12 to 18 Months: Determine Whether the Model Can Scale
By the 12–18 month stage, retailers should have enough operating history to judge whether the store has developed a sustainable rhythm. Footfall and conversion should be relatively predictable, and margins should remain healthy without excessive dependence on discounts.
This is also the stage when capital efficiency becomes critical. Revenue alone does not determine whether a store deserves further investment. A high-sales outlet may still generate weak returns if it requires excessive capex or carries an unsustainable occupancy cost.
The ultimate test is replicability. A store that performs exceptionally well because of an unusually strong location may not provide a reliable blueprint for expansion. Before opening several similar outlets, retailers need confidence that the format can generate healthy economics across comparable catchments.
“One should target to achieve an ROI in the range of approximately 20–30% pa, depending on the format and location. However, beyond the performance of an individual store, the most important factor for us is replicability,” said Bafna.
Early Warning Signs Matter
Retailers should begin looking for warning signals well before a store reaches its planned payback period. Footfall alone is not sufficient. If a store has strong traffic but weak conversion, the issue could lie with assortment, pricing, visual merchandising, customer experience or staff capability. If conversion is healthy but average transaction value remains low, cross-selling and assortment opportunities may need attention.
Inventory is another important indicator. Strong product-level sell-through without heavy discounting suggests that the proposition is resonating with customers. Conversely, ageing stock combined with weak conversion and increasing markdowns can indicate a deeper problem.
“The first 60 to 90 days tell you most of what you need to know. A store showing a conversion rate above 25%, strong cross-selling and healthy organic footfall without discount boards doing all the work outside, is a store that’s going to do well,” mentioned Kapoor.
When Should a Retailer Intervene?
Underperformance during the early months does not automatically mean that a store should be closed. Retailers first need to identify whether the issue is temporary or structural. Incorrect regional inventory, inadequate staff training, weak local marketing or temporary access problems can potentially be corrected.
Structural issues are more difficult to solve. Poor catchment, inadequate neighbourhood footfall, low visibility or a rental structure that is incompatible with local spending power can continue to suppress performance even after operational changes have been made.
A practical intervention framework can help. If sales are materially below plan around the 90-day mark, retailers can review the assortment, pricing, sizes, colours, local marketing and manpower. At six months, the financial performance should receive a deeper review, including the possibility of renegotiating lease terms or adjusting the store footprint. If the outlet continues to lose money by around 12 months without a credible path to profitability, relocation, downsizing or exit may need to be considered.
“Good retail management is also about knowing when to exit and being willing to take a tough call when the economics are structurally not working rather than continuing to put capital and management bandwidth into a store simply because we have already invested in it,” emphasised Bafna.
Ultimately, the goal is not simply to open more stores, but to build a network where every outlet converts space, inventory and invested capital into sustainable returns.